A recent webinar series yielded timely insights about the complexities policymakers may face when addressing climate-related financial risk.
The physical and transition risks associated with climate change have a growing effect on the US financial sector and the real economy. In the fall of 2026, the Climate-related Financial and Macroeconomic Risk Initiative (CFMRI) convened a three-part webinar series in which leading industry experts leveraged their experiences as academic researchers, industry practitioners, and former policymakers to provide insights on how to better understand, manage, and ultimately reduce the impact of climate change on the financial sector and macroeconomy.
The discussion did not focus on steps designed to stop climate change itself. Rather, participants took a risk-management perspective that focused on understanding the potential economic and financial impact of climate change and promoting policy that can reduce the adverse impacts. For those interested in all the details, the full recordings of all three webinars are available on our website.
This blog post synthesizes the common themes that emerged from these discussions: the underlying complexity of the financial and economic transmission channels, the critical importance of more granular perspectives that can identify and explore the components underlying the aggregate impact of climate change, the breadth of impacts that span multiple types of financial and economic policy, and ideas for developing more effective policy.
Complexity Everywhere
The chain of events that result from a changing climate is fundamentally complex and marked by deep uncertainty. In addition to uncertainties surrounding the trajectory of climate change, we see uncertainty and complexity in these factors:
- Policy-related factors: Uncertain response of monetary, fiscal, regulatory, and climate policy; interplay between different types of policy choices; and the timing and pace of those choices
- Private-sector factors: The scale and timing of the energy transition, supply-chain integrity, the efficacy of climate-adaption investments, deterioration of existing capital stock, reallocation of production, technological progress, and relative price change of renewable energy
- Household behavior: The evolution of investor beliefs and subsequent impact on asset prices, employment choices, and migration patterns
These factors interact in complex and unpredictable ways, which means that it isn’t always straightforward to understand who is affected by climate risk and how deeply.
For example, the economic impact of a natural disaster includes both the direct effects from the destruction of property, and the indirect effects that cascade through the economy as behavior changes and firms and markets respond to the event. Prices for residential or commercial real estate may fall abruptly as beliefs change about future climate-related events; the affordability and availability of insurance may respond; and the physical location of economic activity may shift in a way that impacts labor-market outcomes such as employment, wages, and participation rates.
More analytical work is needed to understand the transmission channels and feedback loops that determine the size of the indirect economic effects of climate change.
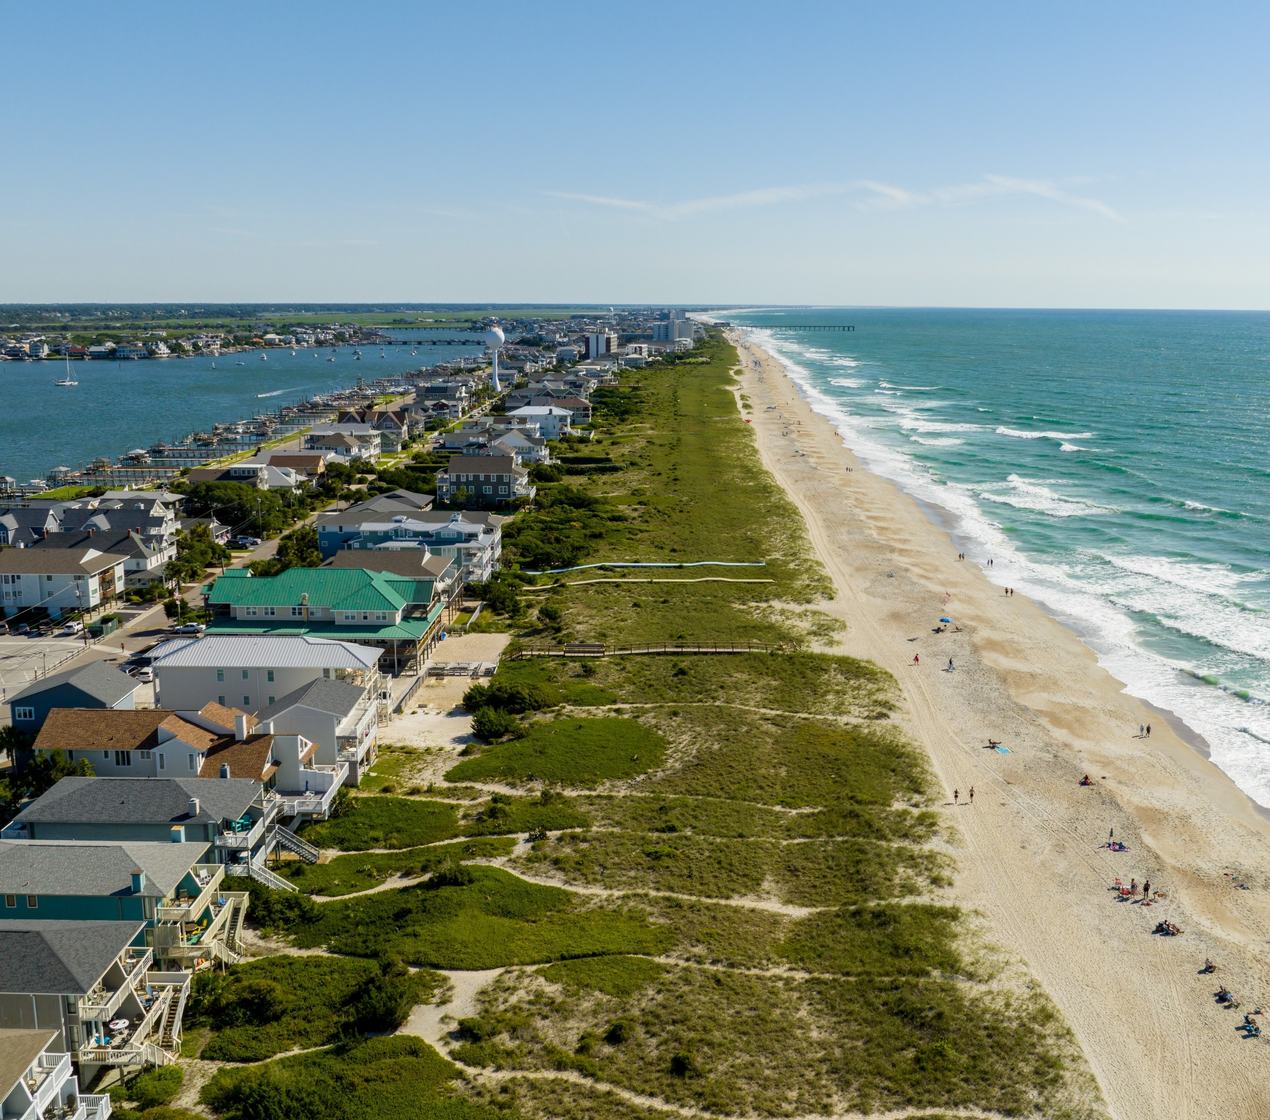
Credit: Matchou / Shutterstock
It is also critical to understand who is actually impacted as financial risk flows through the financial system. Depending on the nature of the shocks and responses, losses may ultimately be borne by different actors, including homeowners; insurers; reinsurers; banks; holders of securitized products; state and local governments via municipal finance; and the federal government, which is the ultimate holder of risk. This flow of risk can lead to systemic consequences if the risk is poorly understood or mispriced. Ultimately, policymakers need to know who bears the risks of climate change to develop informed policy responses.
Granularity Matters
Analysis needs to move beneath an aggregate perspective to show how regions, sectors, and communities face different outcomes related to the financial and economic impacts of climate change.
Aggregate statistics, like national GDP, provide an overall assessment of how climate change affects the economy. But these aggregate data may miss variation when considering policy changes that impact different sectors and communities in distinct ways, depending on the nature of the shocks and the policy response. For example, large businesses can adapt to physical shocks like heat stress by reorienting production toward their less-affected locations or establishments. The economic impacts can vary across regions.
On the financial side, the impact of climate-related risk drivers is likely to vary across different types of financial institutions. For example, small banks may be particularly vulnerable to the impacts of natural disasters, as these banks typically have geographically concentrated portfolios; narrower business models; and few resources to devote to new tools, data, and expertise. As a second example, surveys show considerable heterogeneity in investor preferences related to green investment opportunities, which impact both mitigation and adaption spending.
A particularly valuable aspect of approaching climate-related risk more granularly is that specificity allows insights about who may benefit from certain policy responses and who might suffer. For example, how mitigation policies such as a carbon tax affect different parts of the economy depends on how the revenue from those policies is used. Similarly, communities that are dependent on fossil fuels are likely to suffer more from mitigation policies, so policymakers need to recognize the differential impact of policies on local job markets and economies.
The same type of regional reallocation can happen in housing markets, as supply and demand vary across regions. Variation in regional impact can bubble up to the federal level if federal policies include social goals like loss-sharing or economic equity via development and the implementation of place-based policies.
Broad Policy Relevance
The webinar discussions highlighted the important interplay among different types of financial and economic policymaking, including fiscal policy, monetary policy, financial policy, innovation policy, housing policy, trade policy, and climate policy. Policymakers must consider how climate-related risks impact the ability of each type of policy to achieve its objectives and how these policy actions may interact or create trade-offs in unpredictable ways for households and firms.
On the macroeconomic side, evidence shows that physical and transition risks are having a growing impact on core economic variables like productivity, prices, capital flows, relative prices for energy, and employment. For example, climate change and related policies can impact both the level and volatility of energy prices in ways that challenge central banks like the Federal Reserve, which has statutory mandates tied to full employment and price stability. The ultimate economic impact of climate policies, in turn, depends on how monetary policy responds to things like changes in energy prices and economic fluctuations as a result of those climate policies or the climate shock itself.
Credit: somkanae sawatdinak / Shutterstock
Different types of policies also interact. Climate-related policies such as emissions trading systems or carbon pricing schemes can impact output and inflation in ways that are relevant for central banks. Ultimately, the size of the economic impact is an empirical question. For example, recent research shows that carbon pricing schemes have a limited impact on macroeconomic variables like output, employment, and inflation, potentially because of the response of monetary policy.
On the financial side, regulators interested in the safety and soundness of individual financial institutions or broader financial-stability objectives need to consider how climate-related risk drivers can impact the health of individual institutions or system-wide vulnerabilities. As with the macroeconomic impact, that is an empirical issue about the size of the impact and not a conceptual issue about the mandate of central banks or financial supervisors, which need to incorporate into their policy responses all factors that impact financial and economic outcomes.
Insurance emerged as a central focus in the webinars, given the industry’s role in risk transfer and the deep challenges the industry faces as the underlying distribution of climate-related shocks shift. These shifts raise important public policy questions about the affordability, availability, and coverage of insurance. For example, academic work shows a strong empirical link between rising insurance premiums and financial outcomes like mortgage delinquencies, repayments, and house price declines.
The broad policy relevance of climate-related risk spans an international dimension on both the economic and financial sides. For example, divergences in energy policy in the United States relative to the rest of the world have shifted the US economy to a position as the world’s largest exporter of fossil fuels. These connections show the links among fiscal policy, trade policy, and climate policy.
Effective Policy Design
The complexity, heterogeneity, and policy interactions related to the underlying drivers of the financial and economic impacts of climate change raise difficult challenges for policymakers. To help minimize these challenges, policymakers can consider several attributes to improve the efficacy of policy and make informed choices. These attributes follow a natural flow of policymaking.
First, policymakers can help deepen the capacity of the private and public sectors to understand the emerging risks and potential impacts of climate change. Added capacity could include the development and distribution of more granular data such as the geographic or sectoral composition of assets held by financial institutions, and more work toward understanding economic transmission mechanisms, systemic risk-measurement tools, and the potential interplay between climate- and nature-related shocks.
Households need more information about the risks in the assets they hold. Some webinar participants believe that decision-useful, granular data is a public good, which makes a strong conceptual case for a government role in providing information. Collaboration among academia, industry, and the public sector can help develop the underlying framework for effective government responses.
Credit: Jon Bilous / Shutterstock
Deeper understanding of emerging risks also requires more formal monitoring of emerging risks at both the microeconomic and systemic levels. In the United States, a gap has emerged in recent years as government-led groups working to understand the financial-stability implications of climate change have been disbanded, such as the Climate-related Financial Risk Advisory Committee sponsored by the US Department of the Treasury’s Financial Stability Oversight Council.
Second, policymakers can ensure households and businesses make decisions based on the true risk they face by continuing to recognize the importance of incentives and price signals in policy-design choices. Such choices may include promoting adaptation and resilience through risk-based pricing of financial products and avoiding moral hazard and maladaptation in cases where price signals are distorted, such as through subsidized insurance. Recognizing the true costs of climate-related risk raises difficult choices and trade-offs, however. For example, insurance policy has competing objectives between things like affordability and risk-based signals, so policymakers need to be clear about what goal they are aiming for. In terms of broad private-sector innovation, policymakers should amplify policy objectives by leveraging competitive firms’ incentives to innovate.
Third, policymakers can enhance communication and, where possible, reduce policy uncertainty. For example, long-term planning and sustained policy commitments are important components of effective industrial policy, and evidence suggests that gradual policies are less costly than surprise policy actions. The current environment of wide policy swings can inhibit durable private-sector responses. At the same time, however, the inherent uncertainty around the economic and financial impact of climate change suggests the need for flexibility and a broad suite of robust policies, which creates some tension. Communication needs to leverage objective analytical work about what is happening with the financial and economic impacts of climate change.
Conclusions
The initial CFMRI webinar series highlighted both the importance of climate-related issues facing the US economy and the complexity of the problems that policymakers must address. Effective solutions to complex problems such as these typically require a broad set of perspectives. A key attribute of CFMRI is the ability to bring together a diverse set of experts who view these issues through different lenses. CFMRI will continue to grapple with these issues and look for opportunities for rigorous research and a broad range of perspectives to contribute to effective policy discussions.