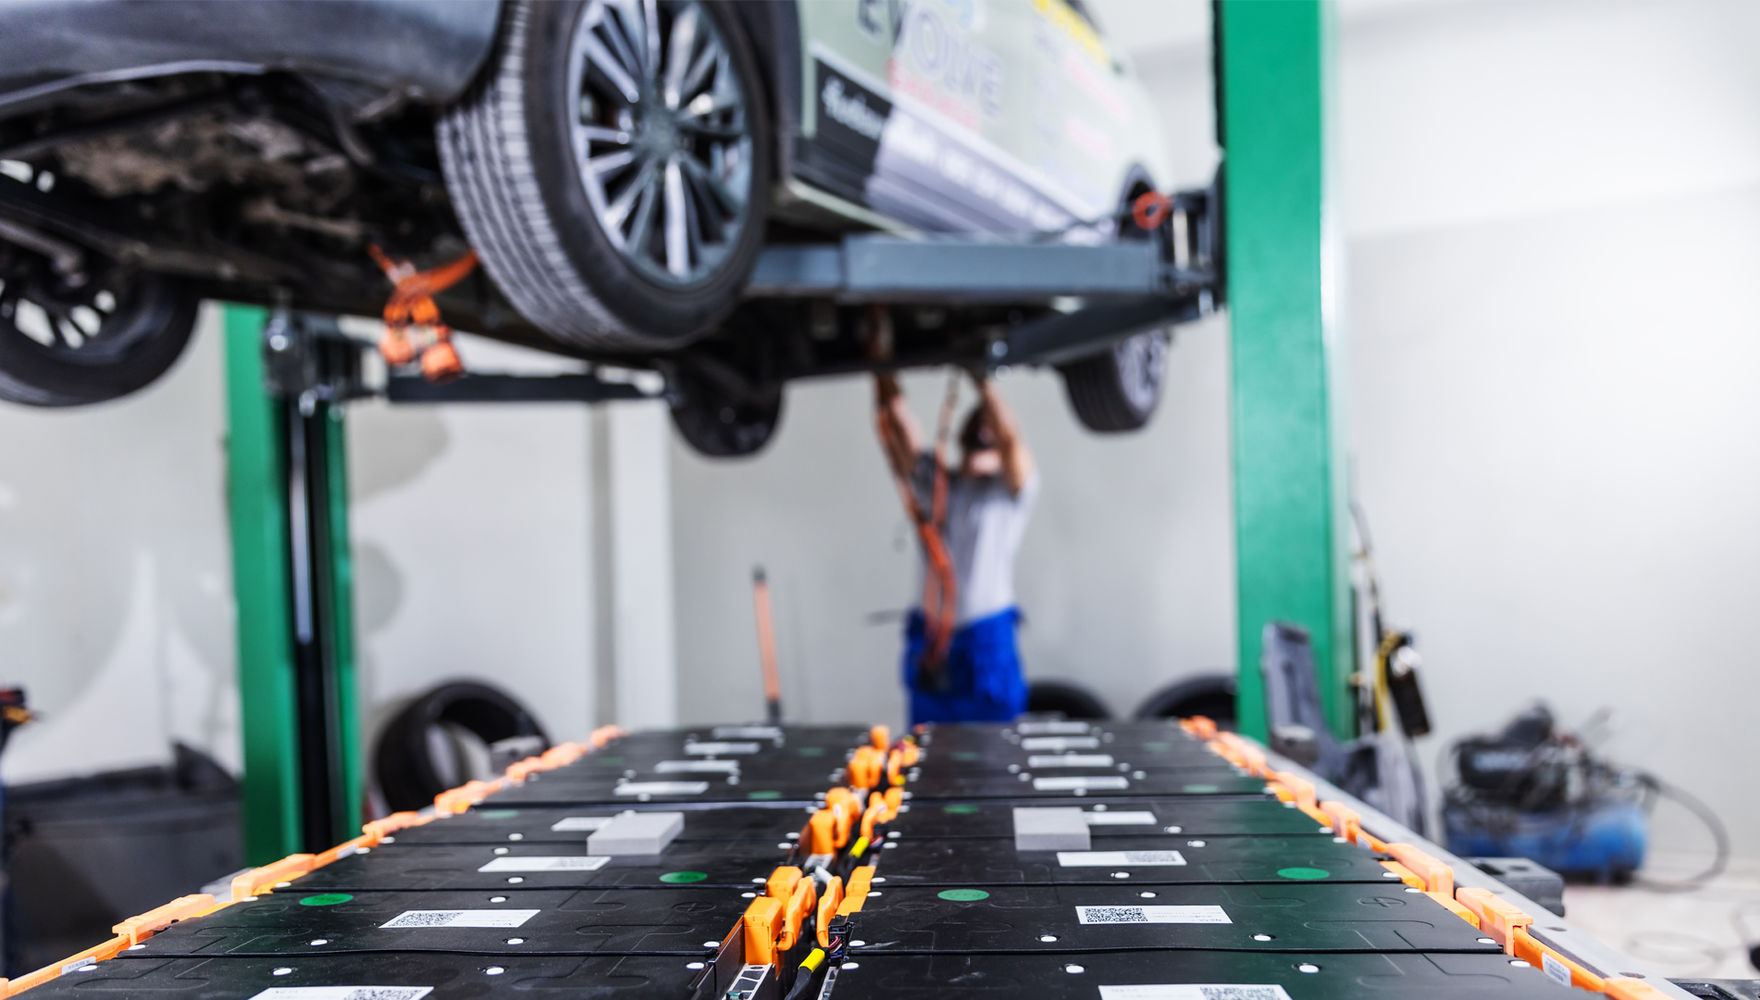
In this episode, host Kristin Hayes talks about the future of clean transportation with Michael Berube in the Resources for the Future podcast recording studio. Berube is the president and CEO of Catalyst Mobility; he’s been leading the organization for the past year and has spearheaded a rebranding of the nonprofit organization, which aims to advance clean, equitable, affordable transportation solutions to move people and goods. His role at the nonprofit combines with experience he’s accumulated in previous positions as a US Department of Energy senior official, corporate executive, and engineer, enabling him to adroitly explore questions and projections regarding the road ahead for clean transportation. Hear what Berube and Hayes discuss about the influence of policy certainty on decisions made by auto makers and consumers, the importance of competing in the global market (rather than relying on national or regional markets), variation among countries and even among US states in electric vehicle adoption, and strategically applying demand pressure to create markets and motivate increased supply.
Listen to the Podcast
Audio edited by Rosario Añon Suarez
Notable Quotes
- Electric vehicles are the future: “There’s absolutely no question we are going to move to a largely electrified mobility system for on-road vehicles. That is clearly the future. The question is the time frame going from here to there.” (10:08)
- Policy certainty creates a stable market: “Regulations can provide a competitive leveling, because as you’re making a transition in a very capital-intensive industry (as you said, huge capital in the auto industry), you need long planning horizons. You need that certainty.” (20:56)
- Global competitiveness is how a company (or industry) will survive: “You have to have technology that competes globally. If you’re a company that has one market—so, if you have the United States saying we’re at this much lower rate, or we have protectionism or tariffs that keep other people out—that can help you in one market, but that doesn’t help you compete globally. The only way to really compete is to actually compete. To have products that are better and affordable.” (26:46)
Top of the Stack
- “Largest Electric Truck Order Will Nearly Double the US Electric Class 8 Fleet” press release from Catalyst Mobility
- “The Architect of Modern China” episode of The Rest Is History podcast
The Full Transcript
Kristin Hayes: Hello, and welcome to Resources Radio, a weekly podcast from Resources for the Future. I’m your host, Kristin Hayes. My guest today is Michael Berube, president and CEO of Catalyst Mobility, a nonprofit focused on advancing clean, equitable, and affordable transportation solutions that move all people and goods. Catalyst Mobility brings together two different NGOs operating in the clean-transportation space—one called CALSTART, one called Forth—and the two are combining forces in late 2026, early 2027. You’ll definitely hear more about that from Michael.
But in his life before Catalyst Mobility, Michael served as a senior leader at the US Department of Energy, where he played a key role in crafting the US transportation decarbonization blueprint. He also held executive leadership roles at Chrysler, so he brings a wealth of both government and corporate experience to our conversation today. We’ll be talking about the future of the transportation sector along a range of dimensions, including the economics of vehicles and fuels, the drive toward cleaner transportation, and how automakers stay competitive in a global market. Stay with us.
Hi, Michael. Welcome to the show. Thank you so much for coming on.
Michael Berube: Thank you for having me. It’s really an honor to be here.
Kristin Hayes: It is my pleasure. Well, I just shared a little bit about your professional history, but we always want to give our guests the chance to introduce themselves, as well. We’d love to hear about your background in your own words.
Michael Berube: When I think about my background and what really brings me to this job, it is a lot about bringing together technology, policy, and government.
In fact, thinking about being here with Resources for the Future (RFF), one of my first examples of work in this area goes back to graduate school. I was taking a class in environmental economics from Robert Stavins, who was a longtime board member here and involved with RFF.
I started really early on in my career, as you mentioned, in the automotive industry. I worked 20+ years in Detroit—it was a great experience, very fun working on cars, but really learning how industry works, how decisions are made. I led several brands and had profit and loss responsibility.
I went then to the federal government, the Department of Energy (DOE), which gave me this perspective of what happens in industry. As you mentioned, I was responsible for all the transportation work at DOE, which includes everything from doing the R&D and developing battery technology for the country, hydrogen, biofuels. But also, especially in the last administration, a lot of that was around deployment of the technology. When I started 10 years ago, there was a real question about, How far could batteries really bring us? How low could we get the cost? 10 years later, a lot of those questions are answered, and it’s a lot about how we deploy at scale.
Having that combination of business and policy together, I think, really defines the experience I’ve had in my current role as president and CEO at Catalyst Mobility. I want to now bring those together in the nonprofit space.
Kristin Hayes: You had all the sectors. I’m actually quite envious of that, because I will say I’ve mostly been in the nonprofit sector, and I do think there’s something about having experienced, as you said, how the decisionmaking works and what the various incentives are, to use an economics term. But it’s a really interesting mix of stuff that brings you here today.
Michael Berube: For sure. I think the experience lends a credibility that’s based in the people you’re talking with. They say, “Okay, we know you’ve been there, we know you’ve had to make these choices of decisions about policy trade-offs between state and national issues,” or about, “You had to make a $2-billion decision for an investment in a private company that shareholders want to pay back on. How do you balance different factors?”
Kristin Hayes: Great. Well, let’s talk a little bit more about Catalyst Mobility for a second. You’ve been there just over a year, I believe. And certainly when I was most familiar with the organization, it was under the brand of CALSTART—that was its name for quite some time. I’m going to ask you to just clarify how the pieces have been coming together, but you’ve recently announced a merger and a rebrand. Tell me a little bit more about how that’s come together, and maybe most importantly, what your goals are there.
Michael Berube: Absolutely. It’s important to look at the history.
Around 32–33 years ago, a group of people had this bold idea in the very early ’90s that there’d be a future clean transportation industry. That seems very obvious today, but it was not so obvious at that time. And that’s really when CALSTART was born. It was born in California around this idea of starting a new space—almost a new industry around clean transportation.
Today, 30 years later, we are a global organization. We’re not just in California. We really focus on, How do we bring clean transportation to scale? How do you get it deployed? How do we ultimately get low-emissions technology that can be both affordable and accessible for all people, whether that’s cars or trucks? So, we decided to rebrand—to really recognize where we are today and where we want to go.
As Catalyst Mobility, we see ourselves as a core catalyst to this change that is happening, a catalyst that helps move the technology forward, moves the industry forward, moves policy forward across that whole intersection of spaces.
And as you mentioned, we also just announced that we are combining with Forth, another nonprofit in the clean transportation space based in Portland, Oregon, that has led a really well-known event, among many things. They do a lot of community-based work. Maybe people know their Roadmap event and conference, which has for the past 10–12 years been where people gather to talk about, What’s the road map to the future? How do we create a road map that is sustainable, that is resilient, but moves us to a more equitable and affordable transportation future?
As a combined organization now, it really gives us strength—makes us, we think, stronger. It allows us to do more. We can have a greater impact. We are a global organization, as well.
I want to mention: While we do have most of our work and activity here in North America and the United States, we do also have a significant amount of work in the Global South, Europe, and Mexico as well.
Kristin Hayes: One quick follow-up question for you, which is about the range of technologies—or, the range of opportunities or mobility instruments that we’re talking about here. You mentioned cars and trucks; those are very familiar to all of us. Are you guys also looking at public transportation? Are you looking at e-scooters? All the things that we have available to us now? Is it really the widest range possible?
Michael Berube: You mentioned my background. I helped develop the US transportation decarbonization blueprint, where we looked at the entire transportation sector and what would it take to really get to decarbonization (or close to that) across the sector: cars, trucks, off-road tractors, planes, trains. I find all of that super exciting. However, as Catalyst, we don’t have quite as broad a piece of that, but what we do look at is everything around personal mobility and the movement of freight in and around the roads and the ships that move them. (Not the maritime, but at the ports.)
The work around mobility is critically important. When you look at emissions—whether it’s greenhouse gas emissions or other emissions—most come from light-duty vehicles, and then heavy-duty vehicles. There’s a lot of focus on decarbonizing the vehicles, and that’s where you’re going to get the scale. However, if we don’t provide mobility options for those where a vehicle isn’t their first choice (a lot of people can’t afford a new vehicle, maybe can’t afford a used vehicle. They live in an environment that’s just not what they want to have), how do we provide clean and affordable options, and micromobility? Even today, I’ve done a combination of the subway, a scooter, and an Uber to get around in all the things I had to do. How do you bring that multimodal combination to people?
Including transit is critically important, not just for people who take transit, but for all those people that don’t take transit. If the people who aren’t in transit are in cars, there’s going to be a lot more congestion.
Kristin Hayes: Yeah. Fascinating. Well, I think our listeners probably know that the transportation sector is probably my favorite sector to talk about. I think it just feels incredibly visible and relevant, and I just have a personal interest in it.
Let’s delve a little bit deeper into the sector. I’ll ask you to maybe do some stage setting at this moment in time. I feel like we’ve had pushes and pulls toward or away from clean transportation. We’ve seen some policy incentives in place. We’ve seen them change. We’ve seen the cost of gasoline and diesel go down during the recession, and then during various points in the pandemic, and then shoot back up. We’re in another point of high prices, among many other factors. Give me context for today. Where are we in that transportation trajectory?
Michael Berube: Part of what we have to think about is the “we” there: Where we in the United States are, where the globe is at. So if we zoom out first, globally, there’s a massive transition happening. We’re now approaching 30 percent of all new vehicles being battery electric. Some pure battery electric, some plug-in hybrid, but basically plug-in vehicles one way or the other. And in the scale of the automotive industry in any part of the world, that is huge. That is absolutely game changing.
But it’s different and it’s uneven. Probably many people know there’s been a higher penetration in some parts of the world than others. Here in the United States—among all the people I work with and talk to, whether senior leaders in car or truck companies, people in the technology space, people that make batteries, everyone said, “There’s absolutely no question we are going to move to a largely electrified mobility system for on-road vehicles.” That is clearly the future. The question is the time frame going from here to there.
And the reason why: When you look at it, and you talk with consumers, and you look at what’s happening, we’ve developed the technology (the collective we), and it works. It gets people where they want to go. It’s low operating cost, and it also has lower maintenance costs long term. If you’re a truck driver, it doesn’t beat you up all the time, because it’s a smoother ride. It’s a product that works well. You have the question of up-front cost versus operating cost, and you’ve got to solve a bit of a chicken and egg. You have infrastructure you’ve got to develop. So, you have these friction points that slow down that transition.
Quite honestly, in the United States, political uncertainty has been created. You have a bit of a culture question, like, Is this move to EVs a cultural thing, or is it just like, “It’s the next evolution in technology?” Cars are different than phones. People name their cars; people have a relationship with their vehicle. When you get to the truck space, it’s a utility tool. If you’re a business owner, I have a truck, it just does what I need. If it’s going to cost me less money, then great, I’m more competitive, so it gets less emotional. But vehicles are emotional, so it’s not uncommon that as people are thinking about a change, they’re like, “Does this work? What does it mean? Does it work for me?”
To kind of wrap up, I think where we are today is at a point of transition. Some parts of the country see it more than others. We have different levels of incentives. And we’ve had ups and downs on the policy front that have not really allowed a consistent approach within the United States. But we have to remember: It’s a global industry, and that 30 percent is just going up and up. So that means we in the United States have to be competitive globally.
Kristin Hayes: Yeah, I hope we have a chance to talk more about that, because I do think that the sense that automakers are operating in a global market is a really important piece of the puzzle. If the global average is 30 percent (and if you happen to know these statistics off the top of your head), where is the United States in terms of those new purchases? Who’s at the top of the list? Is it Norway? Is it Indonesia?
Michael Berube: Norway is famously—I don’t know where their current numbers are—something like 80+ percent. They’re at the very top end.
China is approaching 60 percent, obviously huge in terms of total numbers and percent.
I was recently in Vietnam, and they basically have one large national automaker that’s there, and they made the decision to go 100 percent electric, so they are rapidly growing on the electric front.
And then the United States—we got to about 10 percent. It’s just dipped down a little bit this year as the tax incentive went away. It kind of flattened out and is coming back up. So call it 8 percent to 10 percent overall. 25 percent in California, less in other states. So it’s not even within the United States, either.
Kristin Hayes: Yeah. You’re reminding me of something else I find interesting: I feel like for most of my life, I could name a set of car manufacturers, and it’s been pretty consistent. But in the past 10 years, as a number of new manufacturers have come in, like Rivian in the United States, and then also new Chinese companies like BYD, and other companies that are emerging that are exclusively focused on electric vehicles, we’re also getting a new set of manufacturer players, which I think is really interesting, too. Is that changing the game, as well?
Michael Berube: It absolutely is. Of course, in the United States, I think pretty much everyone knows Tesla for a lot of different reasons, as a name. But when they first started, people were like, “What’s that?” That was maybe one of the first new car companies that really started to take off in volume. Rivian today is a lot more common.
When I go to Europe and South America, though, and I look at cars, I’m like, “What is that?” I don’t even know the names of the brands. There’s been a lot of penetration. A number of these are Asian-based, Chinese-based brands that are growing internationally, as well.
Definitely major new players coming in. They’re shaking up the game a little, and it’s putting pressure on the incumbents. The incumbents are big; they have a lot of capability, and that’s some of what I think we’ll see play out in the coming years. How the old and new players come together, if you will.
Kristin Hayes: Yeah, great. Well, let’s talk for just a bit about consumer demand. If our listeners are regular listeners, they will definitely know that I have an EV, because I did a whole podcast series about it and got way too into it. I’ve really enjoyed exploring life as an EV owner. But I have also heard that, overall, particularly in this country, demand for electric vehicles really wasn’t keeping pace with what some of the policy drivers were pushing for. I think of California in particular as a place where there’ve been pretty high drives toward electric vehicles, but is the demand really there?
What’s your take on that? Is there a mismatch between the policy drivers, where the industry can go, and where consumers are?
Michael Berube: Always a hard question.
I mentioned I ran several brands, did a lot of brand marketing in the auto industry, so I have a sense of consumer sentiment. And when you ask consumers sometimes of something they haven’t envisioned, like when you said, “Would you like a system that helps keep your car in the lane or helps people?” “No, absolutely not. I don’t want it.” But when people then had it, they would say, “I will never buy a car without it.”
Consumers can react to what they see. When you look at consumers who have had electric vehicles, recent data from JD Power (which does a lot of consumer data gathering) shows that 97 percent of those people say, “I am very likely to buy another one.” People who have electric vehicles like them and want to go back to them. When you look at the number of people that say, “I’m interested and I’m going to consider it in the future,” it’s well above the current 9 percent to 10 percent market share we were at, which is an indication that there’s market growth opportunity.
That interest and core desire didn’t really go down as the incentives came down; there was a bursting of a bubble. And then some model availability also retreated. As a result, you had this drop-off in some of the demand.
Tesla hasn’t come out with a new model in a while, and Tesla’s been a big driver of new vehicles. The new Rivian is probably going to drive demand. Model availability is always the number-one indicator of market share when you look at the auto industry, and in the light-duty space, especially.
Talking about consumer demand, let’s broaden from consumer to customer—heavy-duty trucks. Tesla is about to launch the new Tesla semi. They just had their V1 starter production date that started. Those trucks are going to start rolling down the road. They’ve been out and testing with fleets for several years now. Some people say, oh, I heard about that years ago, and they’ve been talking about it forever. It takes five to six years to basically go from product development start to end in a product cycle. If they had come out with a truck in two years, I’d be really worried that it was a good product.
Kristin Hayes: Yeah, like, “Did you guys test it enough?”
Michael Berube: Exactly. They have been doing their homework and doing it right. You’re going to see those around the country. Some of the markets where some of the highest demand initially is are places like Texas, because the differential between electricity and gas prices make it attractive.
One other point on consumer demand and consumer interest: When you look at the entire car park—all the new and used cars, a lot of vehicles on the road—if you look right now, about 3 percent of them are electric, and that number will go up. Another perspective would be if you’re at a street corner waiting for the traffic to go, 1 of every 30 cars you see will be electric. You start seeing infrastructure has also grown quite a bit. You see more of that. You’re starting to see it just a little, but this is going to grow—curbside charging, as well, for people who live in a multi-unit dwelling or an apartment building, essentially, don’t have charging at home. Just the visibility will get more and more people saying, “Oh, I guess there’s more out there than I realized.” And then as they become consumers, the word-of-mouth factor.
So, to your first question, Where are we on the policy expectations versus the market demand? California was up around 25 percent. They had a pullback due to some of the federal government saying that they were not going to approve California’s plans. That’s in the courts right now. We’ll see where that gets resolved. I will say, several years ago, there was an updated set of regulations that targeted getting to 40–50 percent by 2030. At that point in time, was that possible? I think it really was.
Part of the challenge is, How do you forecast where demand will be as it grows? If you look at the global trend, is that possible today? That would be a challenge because we’ve had this kind of pause. One of the things we could talk more about is how regulations help make that market or not. They can’t make the market on their own, but they can do important parts of it.
Kristin Hayes: Yeah. I’ve had the pleasure and privilege recently of talking with a number of different car companies about future policy, since we are in sort of a policy-transition moment. Regularly, we hear that some of the most important things are certainty and durability, because these decisions that car companies are making happen over long timescales. It does take six years just to test something that they’re rolling out. So they need policy signals that last for a long time. The back-and-forth between various political changes over the years has been a challenge. So, happy to hear more about what would be the most beneficial policy-planning process that can happen for those companies.
Michael Berube: When you think about a consumer market in particular, you can’t have a regulation that makes a market that consumers don’t want. That won’t work. But if you have a product that actually says, well, this does meet consumers’ needs. It works and it’s economical—which is where we are getting and have gotten for a good chunk of the population for EVs, maybe not 100 percent, but definitely got 30–40 percent—that would work today. The regulation can help provide certainty for automakers, but they need to know, okay, for the next four or five years, this is the North Star we’re all heading to.
Regulations can also provide a competitive leveling, because as you’re making a transition in a very capital-intensive industry (as you said, huge capital in the auto industry), you need long planning horizons. You need that certainty. You’re hesitant to make something if you’re afraid you’re the only one. So, you can get a certain freezing-out factor. Regulations can provide a bit of a floor. They can’t drive you to a technology that doesn’t exist. The technology’s got to be capable, and it’s got to be affordable on its own, but it can provide a bit of a competitive floor. It can provide a North Star.
And again, especially in a consumer market where you need to build consumer understanding of, oh, there’s a new thing, there’s a new way. It’s just the new technology. How does this work? Will I have enough charging? That takes some time. And if consumers are hearing a whipsaw of like, oh, this is a good thing, this is a bad thing, it’s coming, it’s not, they’re confused and they don’t know. So consumers need to hear consistent messaging.
And I think, honestly, where I felt we were at is, the technology had gotten to the point that this can work. We are starting to get that. We were building some consumer understanding. Then, all of a sudden, there was a big pull the floor out—no, it’s not going to work. We’re going to back away. It’s a bad thing. There’s not enough power. There is. And, all of a sudden, consumers are confused, and then you get this pause. And obviously, well, consumer demand isn’t there, because they’re not sure what’s happening.
And when you look at other countries, I don’t know why they get to where they are. How did Vietnam get to where they are? Part of it is all those things lined up together. Government was investing in infrastructure. There was a clarity of, “This is where we’re going.” The technology works. Customers have questions. Customers in China are like, “Will this work? Will I get enough range?” They have questions, just like anyone else. But when there’s enough consistency, and everyone is communicating something similar, then people can get behind it.
Again, they’ll only get behind it if it works. You can’t just make this up if it doesn’t actually work. But if it really works for people, then you can start communicating more consistently. I think that’s where we need to go, and that’s the role regulations can help provide.
Kristin Hayes: Great. I’m curious, just in the countries that you mentioned, too—I think about cost differentials. As an EV owner, I am able to track what I pay for electricity. I think certainly when I charge at home, it’s cheaper than what it would be to fill up a tank of gasoline. But how much does that matter for the countries that have adopted electric vehicles? Are they places where electricity is particularly cheap? Is this an affordability story, as well, or is that not so much of a factor?
Michael Berube: There’s a few different factors. It’s the individual consumer, but it’s also the countries. Part of what you see happening now globally (and this was starting before the current extremely high gas prices and oil scarcity from the current war), countries were looking at, “What are my imports?”
For big countries, oil is one of their biggest imports. It’s in dollar terms; it’s hard for their currency to manage. And they would say, boy, if there’s an alternative, and that oil all goes to transportation in these countries with the import—if they had an alternative where they could control some of that, they can make some of that energy themselves, they could have a diversification and a more stable price point, that’s very attractive. That becomes an internal economic policy.
And then if they start thinking about, “Well, could we be producers of batteries?” Maybe they don’t have all the critical minerals, maybe they have some. Maybe they are producing the end battery. But they can see themselves in this new industry.
One of the things you have, with changeovers in industry, you think big picture over long periods of time. When there’s big change, it creates opportunities and risks, right? Risk for incumbents, potentially opportunities for new people, also for new countries where maybe a new city or new region where we were making the old widgets, there’s new widgets being made. New regions say, “Hey, I want to start making those widgets, too.” In this case, that could be electric cars, some of the battery technology. So you’re seeing that be a driver globally, as well.
But just everywhere you go, the low operating costs of the electronic vehicle is what really drives the economics of that. And when you look at automating connected vehicles for example, one of the whole ideas is you have a vehicle that now is operating a lot of the day. A typical vehicle today—a personal vehicle sits 96 percent of the time (I think is the stat). If you have a vehicle that’s not sitting but is running all the time, then the low operating cost starts driving the economics.
Kristin Hayes: Yeah. Interesting. I’m glad that we’re talking about these competitiveness issues a little bit more. Incumbent players might be a little bit challenged, but it makes room for new players across a range of supply chains related to transportation.
One thing I wanted to ask you was, as we’ve talked about US policy drivers, consumer preferences, vehicle choices—obviously they’re relevant here, but I think very few of these car companies are operating in single markets. So, in your view, how do global automakers need to be operating to really stay competitive across all of this range of policy, consumers, and general variety that we see across the world?
Michael Berube: As you mentioned, and as I said up front, I’ve worked over 20 years in the automotive industry. There is no automaker (auto or truck, car or big-truck maker anywhere) that can really be competitive in only one market. There are some new start-ups that may be, as a start-up can, initially. But look at Tesla: As a start-up in the United States, initially, it had to go global. The amount of investment you have to make in the products, new technology, automation, and connectivity coming as huge, huge investments.
So when you think about that—and there’s been a number of mergers in the auto industry as a result of that—you have to have the technology that competes globally. So if you’re a company that has one market—so, if you have the United States saying we’re at this much lower rate, or we have protectionism or tariffs that keep other people out—that can help you in one market, but that doesn’t help you compete globally. The only way to really compete is to actually compete. To have products that are better and affordable.
So, if you’re a car company or truck company today, and you’re the CEO of those companies, you are basically thinking, “I might have a pause right now in the US market, but I need to have competitive products price-wise.” That is going to be electric in the future. There’s just not really a question.
And if you’re an automaker, it’s actually also in your interest. It’s lower variation in the amount of powertrains, the engines, the transmissions, the emissions control systems. It’s actually less complex to make that electrified vehicle. It’s lower warranty costs long term. If you’re the CFO at one of these companies, you’re like, “Yeah, absolutely I’d have electric products, but the sales folks have to be able to sell it.” As long as they can sell it, it will make more sense there economically.
And that’s where you see new incumbents globally, largely in China—why they said we’re starting a new auto industry, just like every major industrial country in the world used an automotive industry to help drive up their industrialization. Everywhere in the world, that was true. And China did that same thing, as well, and they said, we’re going to do a lot of that with electric, because we’re starting from new. We can be more competitive there and economically make it work better. So that puts pressure on everyone to compete globally.
And I do think back to the regulations. One of the things you see in the heavy-duty truck space: Europe has more aggressive regulations than the United States. You see higher penetration of heavy-duty electric trucks there. If you’re a truck maker, you’re like, “Well, I can’t quite afford to invest everywhere right now, but I’ve got to be competitive. I’ve got to develop the technology.” You start in one market, and you see more of them starting there. “I’ve got to learn, they’ve got to grow.” They have to scale. And once they can scale, then you’ll see it grow and spread globally.
Kristin Hayes: Yeah. I’m glad you brought us back to trucks, too, because I actually meant to ask you something earlier about that. So, let me circle back to that for just a second.
Back in September, not too long ago from when we’re recording, Catalyst Mobility and a partner, the Smart Freight Centre, announced (I’m going to quote here from your press release for just a second), “A coalition of the world’s largest cargo-owning shippers have enabled the largest electric truck order to date in the United States.” And then goes on to say, “A single deal that nearly doubles the US electric Class A fleet.”
Okay, so we’ve got a big exciting announcement about purchases of electric trucks here in the United States. Why does this deal matter? It’s obviously something that you guys are celebrating and really excited about. Why does it really matter from this sort of demand-pull perspective?
Michael Berube: Yeah. For the average person, Class A is a tractor-trailer truck, like when you think about an 18-wheeler going down the road. 2,500 was the largest order ever, like I said, doubling the current capacity. It’s important because it signals demand—it signals that these are economic factors. And it actually provides scale to help lower the cost.
Like a lot of new technology, new changes, there’s a bit of a classic chicken-and-egg problem. How do you get enough volume to scale up? These are very high investments, as we talked about, so it’s not like you can just throw some money out and try it. We brought together big shippers; think of an Amazon or other big companies like that. Some companies you would never have heard of, but they ship pallets around the country, and they all have an interest in having a lower-emissions profile.
So, we looked at where their trucks are going—what regions. We found 10 hubs across 5 regions that most of these trucks, or a large number, operate in. We could get some geographic concentration—get enough charging. We put all the demand together. We identified 10,000 units that were cost positive, TCO positive, meaning total cost of ownership. And that was us looking before today’s diesel prices. So that was really saying, given these regions, given the exact utility price, given the gas price, given the range these trucks drive, how many of them would be economically positive, so it’d be more beneficial to be a battery-electric truck?
We put out this request for a proposal (RFP) for 2,500. We announced basically a primary reception, which was Tesla, but also a secondary—PACCAR, which is Kenworth, as the brand people would know. Volvo, and you mentioned BYD which goes by Ride in the United States, as secondary. All basically said: With higher volume, we can lower our prices.
And if you’re a truck maker, you’re developing this technology, but if you’re buying a very, very tiny number of parts from suppliers, the cost is really high. Not surprising. They need to get up the volume curve to get the price down. So, we’re trying to help provide that, as well—to get enough charging sessions to make high-power charging. These are megawatt-capable charging, which means they charge pretty fast. These trucks go 300–500 miles. There’s two versions, and they charge fast. So, they charge fast enough. They meet people’s needs.
We’re now in the process of actually fulfilling those 2,500 orders, the charging infrastructure, some that Tesla’s building out, some that other companies are building out. And every day, I talk to people—some of our members, others, there’s increased investment coming in, private sector investment into this space, because they see this is the beginning of something that will scale.
Kristin Hayes: Fantastic. I will keep an eye out. I have noticed, even as I drive around now, the kind of look and feel of the delivery trucks that I see, the larger trucks, there’s definitely some change coming. So it sounds like there’s more change.
Michael Berube: Yeah, for sure. When you see those Tesla semis rolling down the road (we love all our members, not to focus on one company, but), those will be the first ones in volume. And like a Tesla passenger car, they look different—they will catch people’s eye.
Kristin Hayes: All right. Well, Michael, we are at time, which is too bad, because I really could talk about this forever. But let me close with our regular feature, Top of the Stack, where I’m going to ask you to recommend something else to our listeners, whether transportation related or otherwise. I would love to hear what else you’ve been thinking about and reading.
Michael Berube: I like a lot of history, and I’ve been doing podcasts lately. My sons have recommended to me The Rest Is History podcast. It has a really broad range; I was listening to one just recently on the true story of the King Arthur tales.
But a really interesting one in this space talks about China, Mao, the beginning of developing a capitalist model inside of a communist country—in particular, the area of China where the auto industry really started, these economic zones and that whole history—how did this come up? Who were the people behind that, and how did those ideas come up? It intertwines China and the United States. Some of these early people visited the United States, what they saw here, what they learned, what they took back.
So, anyway: The Rest Is History.
Kristin Hayes: Okay, fantastic. Well, thank you so much. I will note for our listeners that we actually had the privilege of recording in person today, as well. It’s very nice to see you in person. Thanks for coming to RFF, and thanks for joining me on Resources Radio.
Michael Berube: Thank you so much for having me.
Kristin Hayes: You’ve been listening to Resources Radio, a podcast from Resources for the Future, or RFF. If you have a minute, we’d really appreciate you leaving us a rating or a comment on your podcast platform of choice. Also, feel free to send us your suggestions for future episodes.
This podcast is made possible with the generous financial support of our listeners. You can help us continue producing these kinds of discussions on the topics that you care about by making a donation to Resources for the Future online at rff.org/donate.
RFF is an independent, nonprofit research institution in Washington, DC. Our mission is to improve environmental, energy, and natural resource decisions through impartial economic research and policy engagement. The views expressed on this podcast are solely those of the podcast guests and may differ from those of RFF experts, its officers, or its directors. RFF does not take positions on specific legislative proposals.
Resources Radio is produced by Elizabeth Wason, with music by RFF’s own Daniel Raimi. Join us next week for another episode.